A roof can look acceptable from the ground and still create a difficult insurance conversation. If you are asking, does roof age affect insurance, the practical answer is yes. Age can influence whether an insurer will write or renew a policy, what deductible applies, how a claim is settled, and whether coverage is limited to actual cash value rather than full replacement cost.
That does not mean an older roof is automatically uninsurable. Condition, material, maintenance history, local weather exposure, and the insurer’s underwriting guidelines all matter. For homeowners and commercial property leaders, the best position is to understand the roof’s real condition before a renewal notice, storm claim, or active leak forces the issue.
How roof age affects insurance decisions
Insurers use roof age as a quick indicator of risk. As roofing materials approach the later portion of their expected service life, they are generally more vulnerable to wind uplift, hail damage, worn flashing, deteriorated sealants, ponding water, and leaks. A claim on an aging roof may also be harder to separate from ordinary wear and tear, which standard property insurance does not cover.
For a homeowner, the concern is often an asphalt shingle roof that is 15 to 20 years old, depending on its material quality, installation, ventilation, and storm history. In Arkansas, Oklahoma, and Texas, hail, high winds, heat, and rapid temperature shifts can shorten a roof’s useful life compared with its original product estimate.
For commercial buildings, the question is more complex. A 15-year-old TPO, EPDM, PVC, modified bitumen, metal, or built-up roof may still be a sound system if it has been professionally maintained. But deferred repairs, recurring leaks, saturated insulation, membrane shrinkage, open seams, or drainage problems can make its age much more significant to an underwriter.
Insurance companies do not all use the same age cutoff. Some may require an inspection once a roof reaches a certain age. Others may decline new coverage, restrict wind and hail coverage, increase premiums, or require replacement before renewing. The policy language and carrier guidelines control, so it is worth asking direct questions before making assumptions.
Replacement cost vs. actual cash value
One of the most consequential insurance changes for an older roof is how a covered loss is paid.
With replacement cost value coverage, the policy may pay the cost to repair or replace covered storm damage, subject to the deductible and policy terms. With actual cash value coverage, the insurer typically deducts depreciation based on the roof’s age and condition. That can leave a property owner responsible for a substantial share of replacement costs after a covered hail or wind event.
Consider a roof with a replacement cost of $20,000. If the insurer values an older roof at $8,000 after depreciation, a storm claim may be settled from that lower amount before the deductible is considered. The gap can be significant, particularly when the roof needs to be replaced promptly to protect the interior of the home or facility.
Commercial policies may include additional layers of complexity, such as coinsurance requirements, endorsements, sublimits, wind or hail deductibles, and business-interruption considerations. A facility manager should review these terms with their insurance professional and confirm that the building value, roof system, and loss exposure are properly documented.
Age alone does not tell the whole story
A roof’s installation date is important, but a documented condition assessment carries more weight than age alone. Insurers and adjusters may look for evidence that the roof has been responsibly maintained and that damage was caused by a covered event rather than long-term neglect.
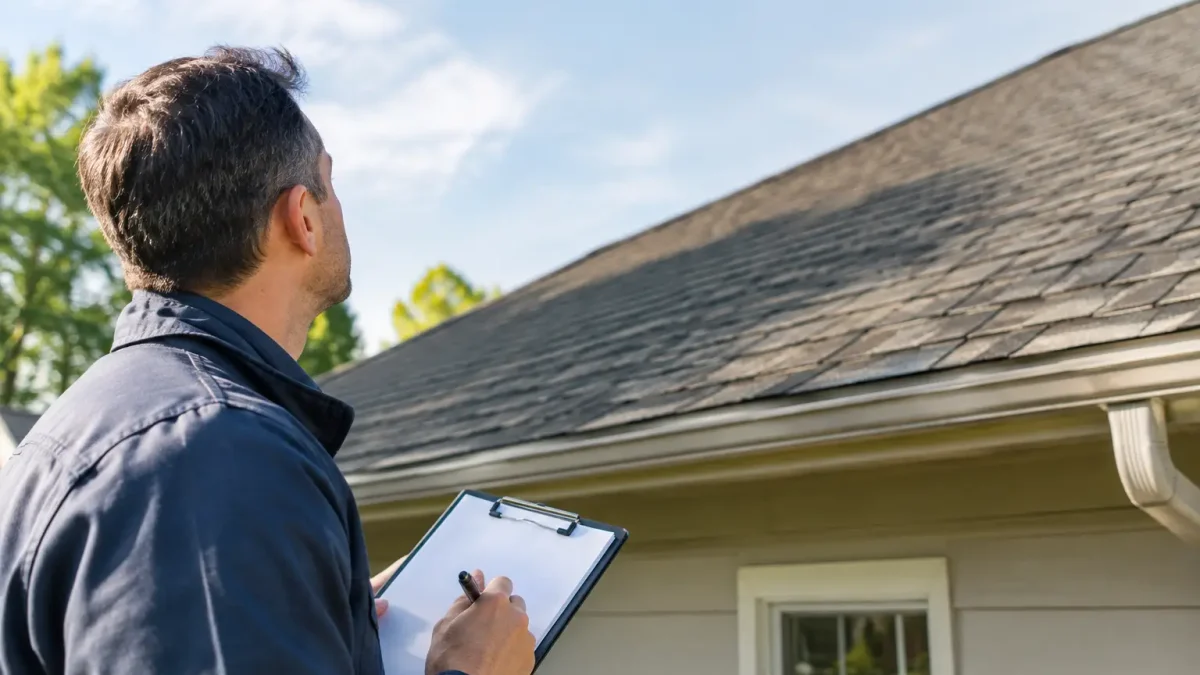
A professional inspection can identify issues that are not visible from the ground, including lifted shingles, granule loss, damaged pipe boots, cracked flashing, soft decking, membrane punctures, failing seams, clogged drains, and areas of ponding water. On commercial roofs, infrared moisture scanning or core samples may be appropriate when there is reason to suspect wet insulation beneath the surface.
Maintenance records matter as well. Keep inspection reports, repair invoices, photographs, warranty information, storm-damage documentation, and records of drainage or gutter cleaning. These materials help establish a timeline and can make it easier to demonstrate the difference between a sudden weather event and a pre-existing condition.
When should you schedule a roof inspection?
Do not wait for an insurer to request one. A proactive inspection is especially wise when your roof is nearing the later stage of its expected service life, your policy is up for renewal, or your area has experienced hail, tornadoes, high winds, or heavy rainfall.
Homeowners should also schedule an inspection after a major storm, even if there is no obvious leak. Hail and wind damage can compromise shingles, ridge caps, flashing, and vents without producing an immediate interior symptom. Catching damage early can prevent moisture from reaching decking, insulation, ceilings, and personal belongings.
For commercial property, regular inspections should be part of a preventative maintenance program. Spring and fall inspections, plus post-storm evaluations, allow teams to address minor defects before they interrupt operations. This is particularly important for warehouses, healthcare facilities, schools, retail centers, multifamily properties, data centers, and other buildings where a roof leak can affect occupants, inventory, equipment, or revenue.
Steps to take before a renewal or claim
If you have an aging roof, start with facts rather than fear. Confirm the roof’s approximate installation date, material type, prior repairs, warranty status, and recent storm exposure. Then arrange a qualified inspection and request clear documentation of the roof’s present condition.
If repairs can safely extend the roof’s service life, address them promptly. Replacing failed sealant, repairing flashing, securing loose materials, correcting drainage, and cleaning gutters or drains can reduce the chance of a preventable loss. For low-slope commercial systems, restoration or a liquid-applied coating may be a viable option in some situations, but only when the existing system is an appropriate candidate. A coating should not be used to hide trapped moisture or widespread system failure.
If replacement is the right decision, select a system that fits the building, climate, and insurance requirements. Impact-resistant shingles may be worth considering in hail-prone areas. Commercial owners may need to evaluate wind uplift ratings, insulation needs, drainage design, attachment methods, warranty coverage, and how the work will affect building operations.
Before filing a claim, document any visible storm damage and take reasonable steps to prevent further loss. Emergency tarping or temporary repairs may be necessary after severe weather. Avoid authorizing permanent work until you understand your policy obligations and the insurer has had an opportunity to inspect, unless immediate repairs are needed to protect people or property.
Can an insurer require roof replacement?
Yes. An insurer can require repairs or replacement as a condition of issuing, renewing, or continuing coverage, depending on the policy and state regulations. The notice may cite the roof’s age, observed condition, prior losses, or inspection findings.
If you receive that notice, act quickly. Ask what specific condition prompted the requirement, what deadline applies, and what documentation the insurer needs after the work is complete. A professional roofing contractor can provide an inspection report and explain whether the roof may be repairable or whether replacement is the safer long-term path.
For commercial owners, replacement planning should also account for occupant safety, access, noise, material staging, weather contingencies, and business continuity. A well-planned project protects the building without creating unnecessary disruption for tenants, employees, customers, or operations.
Protect the roof before it becomes an insurance problem
An aging roof does not have to become a surprise expense or a coverage crisis. Regular inspections, timely repairs, accurate records, and clear communication with your insurance professional give you more options and more time to make sound decisions.
A roof is one of the property’s first lines of defense. Treating its condition as an ongoing responsibility helps protect the people, operations, and investments beneath it.
 Capstone Marketing